Same business day · often within 2 hours*
What would your mortgage actually look like? Find out today.
Buying, refinancing, or the bank said no — get your real numbers and mortgage options the same business day.
*Once your completed application and required information are received.
- 30+ Years
- Mortgage experience
- Same Business Day
- Assessment goal*
- Multiple Lenders
- Bank, alternative & private
- Ontario
- Homebuyers & homeowners
Who we help
Your mortgage situation doesn't have to be straightforward.
Different situations can require different mortgage strategies. Start by helping Lumera understand yours.
- First-time homebuyerNot sure what you qualify for — or what you can comfortably afford.
- Self-employedYour income may not fit neatly into traditional lender criteria.
- Higher debtSee whether refinancing or debt consolidation could improve your monthly cash flow.
- Credit challengesPast credit issues may be making traditional financing more difficult.
- Consumer proposal or bankruptcyUnderstand what mortgage options may still be available.
- New to CanadaYou're building your financial history here and want to understand your options.
- Alternative or private mortgageYou may need financing now, and a plan for what comes after.
Not sure where your situation fits? That's okay.
Start My Free Assessment
When the bank says no
A bank saying “no” doesn't always mean you have no options.
Lumera looks at why it happened, which other lending options may fit, and what would need to change to get you where you want to go.
- Understand why
- Explore your options
- Know what comes next
Client experience
Mortgage decisions are personal. So is our approach.
“Paul knows B lenders and private mortgages inside out. He was diligent, genuinely cared about getting it right for us, and he got results.”
“Our bank said no. Lumera found a structure that worked and explained every trade-off.”
“Self-employed income made everything complicated. It was presented properly and we were kept updated.”
Paul Pham
Mortgage Agent Level 2
Creator of the Lumera Mortgage Assessment
With The Mortgage Trail · Brokerage Licence #13052
With 30+ years of experience, Paul helps Ontario homebuyers and homeowners navigate complex mortgage situations with a clear path forward.
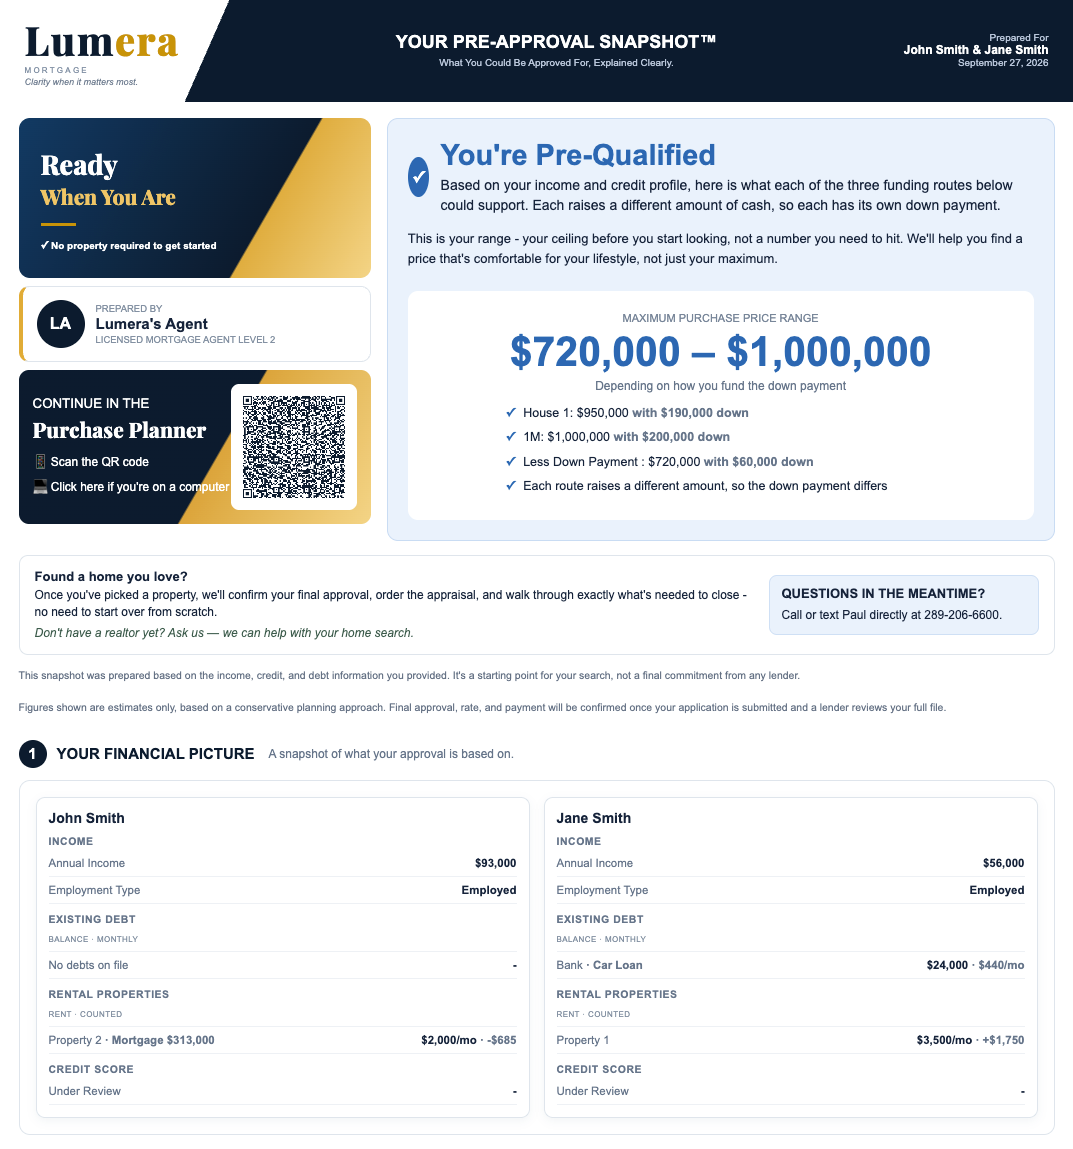
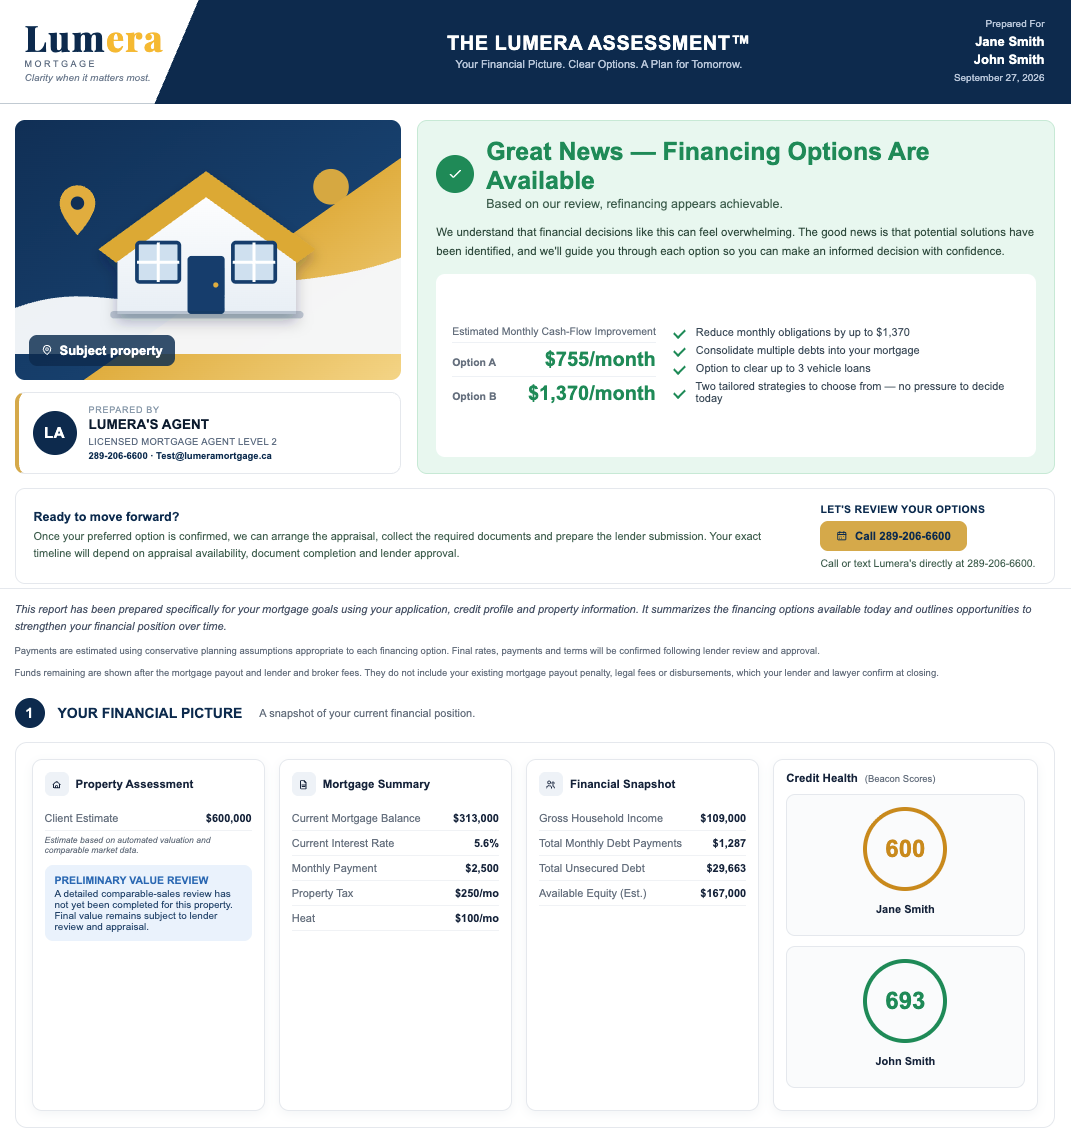
The Lumera Mortgage Assessment
Know where you stand — the same business day.
An application tells us about you. The Assessment tells you what your options look like. Lenders control approvals — Lumera controls how fast you understand your options.
How it works
- 1
Tell us your situation
About 2 minutes. No credit check to begin.
- 2
Lumera reviews the details
Your goals, finances and property are reviewed.
Your Assessment arrives
Same business day — often within 2 hours.*
What you receive
Where you stand
A clear picture of your current situation.
Your options
Potential financing paths that fit you.
The numbers
How each scenario compares, side by side.
The trade-offs
Why one option may make more sense.
Your next step
Written direction on what to do next.
Free · No obligation · Available 7 days a week
*Once your completed details are received. Not a lender approval.
Alternative & private mortgages
A private mortgage should solve a problem — not become a permanent one.
If private financing makes sense today, Lumera also wants to understand why you're using it, how long you may need it and what a realistic next step could look like.
Today
Private financing
Next
Alternative financing
Goal
Traditional financing
Where realistic based on your individual circumstances. Not guaranteed.
The Lumera approach
Mortgage advice should leave you with answers — not more questions.
You should finish with a clearer understanding of:
- Your situation
- Your options
- What to do next
Less uncertainty. More clarity.More confidence in your next step.
- 01UnderstandWhere you stand today
- 02CompareReal options, side by side
- 03PlanToday's mortgage and the next one
Frequently asked questions
Straight answers before you start.
What is a Lumera Mortgage Assessment?
It's a written review of your mortgage situation. It shows where you stand, the mortgage options that may be available to you, how the numbers compare, the trade-offs of each, and a recommended next step.
Is the Assessment the same as a mortgage application?
No. The application gives Lumera the information about your income, debts, credit, property and goals. The Assessment is what Lumera prepares after reviewing that information — it turns it into options you can actually understand and compare.
How quickly will I receive my Assessment?
Our goal is to provide your initial Assessment the same business day, often within 2 hours, once your completed application and required information are received. Lender approval timelines are separate and set by each lender.
What information will I need to provide?
To start your Lumera Assessment, we’ll ask about your mortgage goals, income, debts, down payment and property details. You don’t need to have all your supporting documents ready at this stage. Once your Assessment is complete and you decide to move forward, we’ll ask for any additional information and documents needed for your specific situation. This may include identification, proof of income, a current mortgage statement and a property tax bill. We’ll provide a clear, personalized checklist so you know exactly what is required.
Does getting an Assessment affect my credit?
Yes. To properly assess your mortgage situation, we consider your income, debts, credit and property details. This includes a credit check to confirm your credit score and reported debts, helping us assess which mortgage options may fit your needs. Nothing is checked without your permission. We ask for consent first, and each borrower provides their own authorization. The credit inquiry may appear on your credit history and could have a small impact on your score. Before consenting, you can use our calculators and speak with a mortgage agent without a credit check.
What if my bank already declined me?
A decline from one bank doesn't always mean there are no options. Lumera looks at why it happened, which other lending options may fit, and what would need to change.
Can Lumera help if I'm self-employed?
Yes. Self-employed income often needs to be presented differently to lenders. Your Assessment explains which options may fit how your income is earned and reported.
Can Lumera help after a consumer proposal or bankruptcy?
Yes. Mortgage options may still be available during or after a consumer proposal, or after a bankruptcy has been discharged. Some traditional lenders may require approximately two years of re-established credit after completion or discharge. Other lenders may have different requirements and could offer options sooner. A Lumera Assessment reviews your complete situation to identify what may be possible now and, when necessary, help you plan toward better options in the future. All financing remains subject to lender requirements and approval.
Does Lumera offer alternative and private mortgages?
Yes. When alternative or private financing makes sense, Lumera also looks at how long you may need it and what a realistic next mortgage could look like.
Does completing an Assessment guarantee mortgage approval?
No. The Assessment helps you understand your options and next steps. Final approval is always up to the lender.
Do you serve both homebuyers and current homeowners?
Yes. Lumera works with homebuyers and homeowners in Ontario, including purchases, renewals, refinancing, debt consolidation, home equity, and private mortgage situations.
Start here
You don't need to know which mortgage you need.
Start by understanding your options.
Start your Lumera Mortgage Assessment and get a clearer picture of where you stand, what options may be available and what your next step could look like.